Independent UAE Credit Card Advisory & Comparison
Find the UAE Credit Card Built for Your Financial Profile
Navigate the Emirates' premier banks with private-bank discipline. Compare certified Shariah-compliant and conventional credit cards from ADCB, Emirates NBD, Emirates Islamic, and Dubai Islamic Bank without bias.
Quick Explorer:
Everyday Cashback
Airport Lounges & Miles
Shariah-Compliant
AED 5,000 Min. Salary
Free for Life
19+ Verified Cards
4 Premier UAE Banks
0 Impact on AECB Bureau Score
Ajman Free Zone Reg: ANFZ/2026/8941
Methodology
How EQ Supply FZ Streamlines Your Selection
Applying blindly across multiple UAE banks damages your credit rating with unnecessary AECB hard inquiries. Our structured comparison protects your eligibility.
01
Filter & Benchmark
Compare interest rates, annual fee waivers, minimum salary thresholds, and airport lounge perks across verified UAE banks side-by-side.
02
Check Profile Eligibility
Run our client-side eligibility calculator to match your verified monthly salary, employment category, and residency without credit checks.
03
Fast-Track Advisory
Receive guided documentation checklists for Emirates ID, salary transfer mandates, and direct bank routing to expedite card issuance.
Market Leaders
Explore All 19 Cards →
Top Rated UAE Credit Cards
High-performing options across cashback, international travel, and Shariah-compliant categories.
ADCB
•••• •••• •••• 3650
Abu Dhabi Commercial Bank
Cashback
ADCB 365 Cashback Card
Maximum domestic everyday spend return on dining, groceries, and telecom utilities.
Min. Salary
AED 5,000
Annual Fee
AED 367.50 (Yr 1 Free)
Rewards Rate
Up to 6% Cashback
Advisory Insight: High-velocity everyday domestic card. Requires min. spend of AED 5,000/mo to trigger enhanced cashback.
- 6% cashback on dining spends across the UAE
- 3% cashback on grocery and supermarket transactions
- Complimentary airport lounge access via Mastercard
EMIRATES NBD
•••• •••• •••• 5521
Emirates NBD
Family & Utilities
Emirates NBD Duo Card
UAE's benchmark family savings card: 5% back on school fees, groceries, and bills.
Min. Salary
AED 12,000
Annual Fee
Free for Life
Rewards Rate
5% Plus Points
Advisory Insight: Best household savings card in Dubai. Free for life with dual network support to maximize education fee cashback.
- 5% rewards on school fees and education tuition
- 5% rewards on groceries and utilities (DEWA/SEWA)
- Zero annual membership fees forever
EMIRATES ISLAMIC
•••• •••• •••• 8820
Emirates Islamic
Shariah Compliant
Cashback Plus Signature
100% Shariah-compliant returns on fuel, groceries, and telecom utilities.
Min. Salary
AED 10,000
Annual Fee
AED 315 (Waivable)
Rewards Rate
Up to 10% Cashback
Advisory Insight: Certified Ujrah contract structure with zero compounding interest. Highly recommended for Shariah-conscious families.
- Up to 10% cashback on supermarkets and petrol stations
- Unlimited global lounge access at 1,000+ airports
- Certified Islamic structure (Ujrah principle)
Strategic Financial Advisory
The UAE Credit Card Portfolio Blueprint
Most UAE residents lose thousands of dirhams annually by applying for cards based on billboard marketing. As independent financial advisors, EQ Supply FZ designs balanced credit portfolios that maximize cash returns while protecting your borrowing capacity.
Portfolio Strategy
The "Two-Card" Architecture
Never rely on a single card for all transactions. Strategic wealth management in the UAE dictates pairing:
- Card A (Domestic Essentials): 5%–6% cashback on groceries, schooling fees, and DEWA utility bills (e.g. ENBD Duo or ADCB 365).
- Card B (Cross-Border Travel): 0% FX bank markup + unlimited worldwide lounge access (e.g. ADCB Traveller).
* Holding 4+ random cards incurs redundant annual maintenance fees without compounding rewards.
Central Bank Compliance
Understanding Your 50% DBR
Under Central Bank of the UAE regulations, your total monthly debt obligations cannot exceed 50% of your verified gross salary:
The 5% Rule: Banks calculate 5% of your total credit limit as an active monthly debt obligation, even if your outstanding balance is AED 0.00!
We advise clients to right-size inactive card limits prior to applying for auto loans, mortgages, or premium cards.
AECB Risk Safeguard
Protecting Your AECB Score
Submitting online applications simultaneously to 3 or 4 UAE banks triggers multiple "hard inquiries" on your Etihad Credit Bureau report within days:
- Multiple hard credit hits drop your credit score by 15–30 points.
- Underwriting algorithms perceive sudden multi-applications as financial distress.
- EQ Supply FZ conducts soft pre-qualifications that produce zero bureau footprint.
Ajman Free Zone Entity
Certified Financial Advisory: Protecting Your Net Yield
Operating with the independence of a private wealth desk, EQ Supply FZ bridges the gap between complex bank underwriting rules and your real-world household and commercial expenditure. We model your Debt Burden Ratio (DBR) and AECB credit score trajectory before any applications are routed.
Market Transparency
UAE Card Marketing Claims vs. Underwriting Reality
Behind every promotional headline from UAE banks lie nuanced schedules of charges, minimum spend thresholds, and category caps. Review our advisory breakdown before signing any cardholder agreement.
| Bank Marketing Claim | The Underwriting Reality & Hidden Caps | EQ Supply FZ Advisory Recommendation |
|---|---|---|
|
"Up to 10% Cashback on All Grocery & Fuel"
Promotional Acquisition Headline
|
Requires a minimum retail spend threshold (e.g. AED 5,000/month) before any cashback activates. Cashback is strictly capped at AED 200 per category monthly. Spends above the cap revert to 0.5%.
|
Calculate your actual monthly grocery basket. If your household spends AED 3,000/mo, you will hit the cap and extract maximum return without overspending.
|
|
"Free Unlimited Global Airport Lounge Access"
Travel Cards Pitch
|
Many Visa and Mastercard programs mandate an international foreign currency spend of at least $1 within the calendar year to unlock access; otherwise, cardholders face a $32 per visit chargeback. Guests are often charged unless specified as Infinite.
|
Perform a small international online purchase (e.g. $2 subscription) upon activating your card to keep the LoungeKey or Mastercard Travel Pass profile permanently unlocked.
|
|
"Zero Annual Fee Forever (Free for Life)"
Starter Card Campaigns
|
Zero-fee cards often compensate by imposing elevated foreign currency exchange margins (up to 3.49% vs 2.85%) and minimal reward point conversion rates.
|
Use Free-for-Life cards exclusively for domestic AED transactions and bill pay. Never swipe a zero-fee starter card while traveling overseas.
|
|
"0% Easy Payment Plans (EPP) for 12 Months"
Retail Merchant Offers
|
While interest is 0%, banks charge a non-refundable one-time processing fee (typically 1.5% to 3.5% of the transaction) plus early cancellation penalties if settled early.
|
Always calculate the processing fee against your liquid savings rate. If the processing fee is AED 150 on an AED 5,000 purchase, you are paying an effective 3% upfront.
|
Perks Verification
Auditing Real-World Lifestyle Privileges
Our advisors verify lounge entry prerequisites and dining merchant lists so you never face surprise entrance fees or denied reward points.
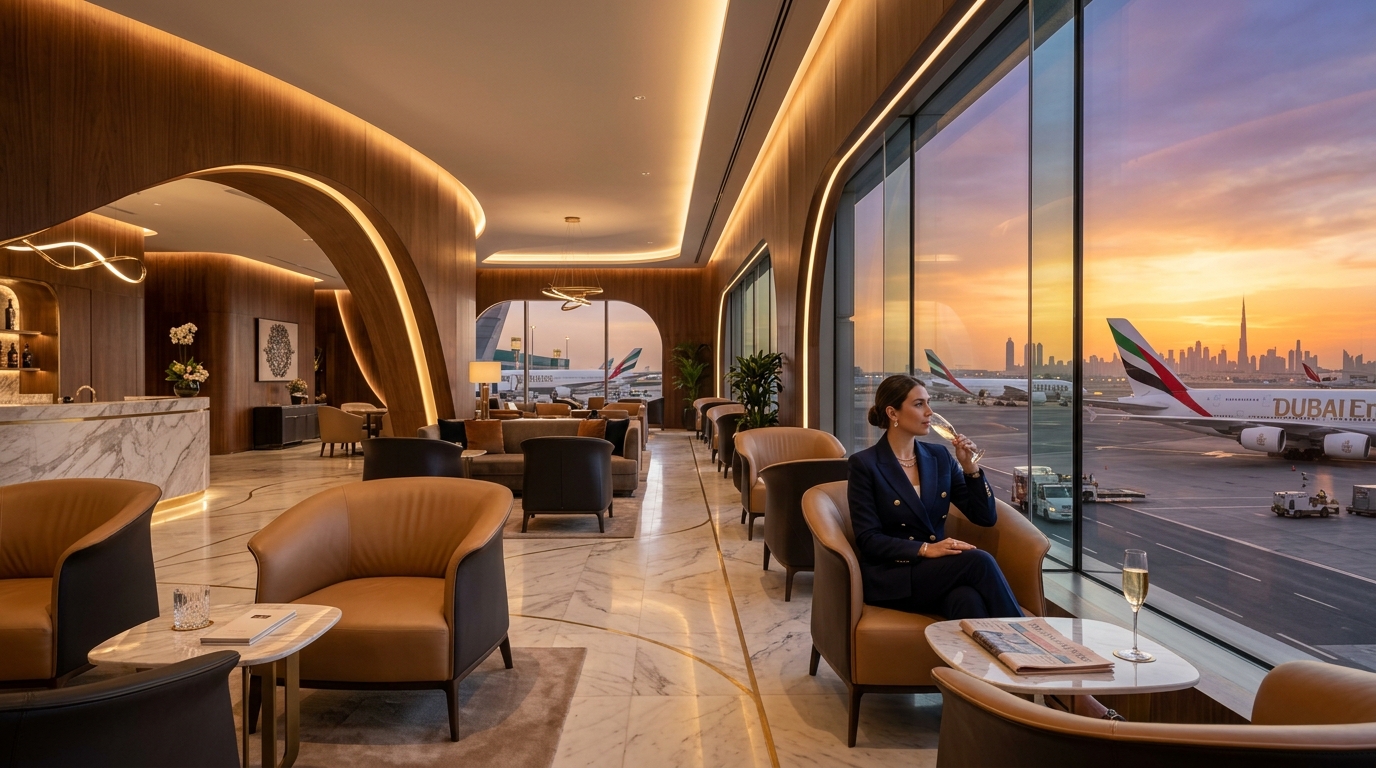 Travel & LoungeKey
VIP Lounge Access Protocols
Many cards advertise "Unlimited Global Airport Lounge Access" but mandate a minimum foreign currency transaction (USD 1+) within the previous 12 months, or charge guest fees of USD 32 per person. We highlight cards with true unrestricted lounge access for you and complimentary guests.
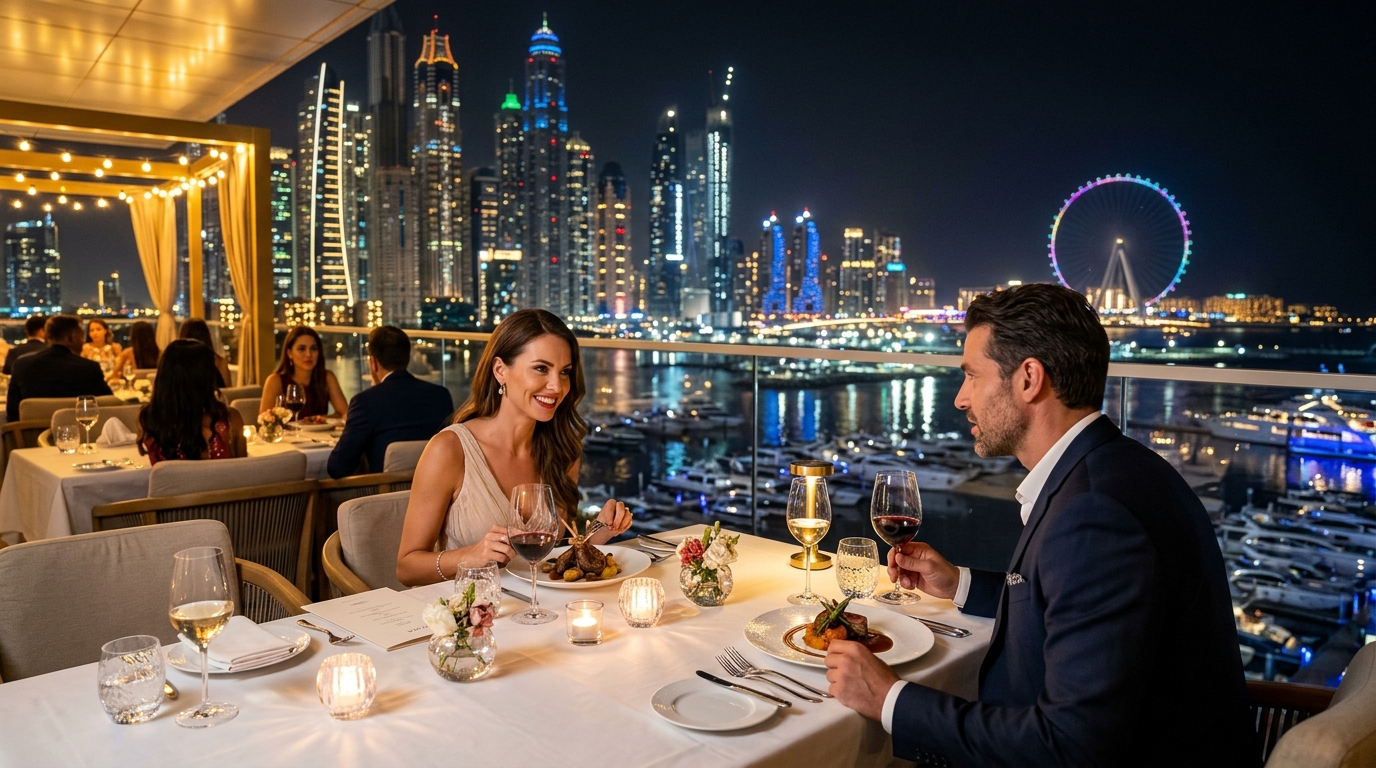 Dining & Lifestyle
Dining Cashback & Entertainer Deals
Extracting top returns on luxury dining requires balancing high headline cashback (up to 6% with ADCB 365 or 5% with ENBD Duo) against monthly category caps. We model your actual dining out frequency against annual card renewal fees to ensure net-positive returns.
Commercial & Free Zone Banking
Corporate Solutions for UAE Free Zone Enterprises
As an entity incorporated in the Ajman NuVentures Centre Free Zone, EQ Supply FZ possesses firsthand understanding of the banking friction faced by newly formed businesses, LLCs, and Free Zone professionals across the UAE.
Traditional retail bank algorithms routinely reject employees of unlisted Free Zone entities or demand mandatory salary transfer mandates that are inconvenient for corporate treasury management.
We bridge this gap through structured financial advisory:
•
Corporate Company Listing Advisory: Guiding your Free Zone establishment through bank employer listing accreditation so all employees qualify for tier-1 credit cards.
•
Secured Fixed-Deposit Corporate Lines: Assisting foreign investors and startup founders with 100% approval corporate cards backed by flexible bank deposit liens.
•
WPS & Commercial Account Integration: Seamless corporate bank onboarding with ADCB, Emirates NBD, and digital business banks.
Free Zone Client Advisory Desk
Entity Authority
Ajman NuVentures Centre Free Zone
United Arab Emirates • Trade License ANFZ/2026/8941
Advisory Scope
Commercial Marketing, Trade License Banking Setup, Retail Card Matching
Need Corporate Assistance?
Speak with our business banking coordinator for bespoke corporate card setups and employer listing reviews.
Market Perspective
Navigating the UAE Credit Ecosystem With Confidence
The United Arab Emirates offers one of the most competitive consumer finance markets globally. However, choosing the wrong product can result in excessive foreign exchange markups, unearned fee penalties, and suboptimal rewards accumulation.
Under Central Bank of the UAE regulatory frameworks, financial institutions maintain distinct eligibility tiers based on verified employer listings, salary transfers, and Etihad Credit Bureau (AECB) risk metrics.
EQ Supply FZ acts as your independent analytical counterpart. We translate complex product disclosure statements into transparent comparison benchmarks, ensuring you apply only where your profile holds the highest probability of approval.
Entity Verification
Registered Corporate Name
EQ Supply Trading FZE LLC
Licensing Jurisdiction
Ajman NuVentures Centre Free Zone, United Arab Emirates
Business Scope
Commercial Marketing, Advisory Support & Financial Intermediary Portal
* EQ Supply FZ does not issue credit cards or provide balance lending directly. All approvals remain at the sole discretion of the issuing bank.
Client Experiences
Trusted by Professionals Across the Emirates
See how UAE residents and business managers leverage EQ Supply FZ for impartial financial product matching.
"I was turned down by one bank because my employer was newly incorporated in Dubai Media City. The EQ Supply team helped me identify a bank with established Free Zone employee programs. The card was issued within 5 business days."
Omar K.
Senior Technology Director, Dubai
★★★★★
"The Shariah filter was essential for our family. Being able to compare Emirates Islamic and Dubai Islamic Bank side by side with the exact Murabaha profit structures gave us complete confidence."
Fatima A.
Executive Administrator, Abu Dhabi
★★★★★
"As a new trade license holder in Ajman, finding business banking and card setup support without huge minimum balances was challenging. EQ Supply guided us cleanly through the required paperwork."
Rajesh M.
Managing Partner, Trade & Logistics
Ready to Discover Your Ideal Credit Card?
Take our 60-second eligibility quiz or compare all 19 verified UAE bank credit cards side-by-side today.